FEDERAL CIVIL SERVICE • RETIREMENT INTELLIGENCE BRIEFING
FEDERAL RETIREMENT INSIDER.
Special Editorial Report • Sponsor: TSP Wealth Builder • Independent Educational Publication
★ MOST READ THIS MONTH | 3 MIN READ | 18,420+ SHARES
7 TSP Mistakes [Federal Employees] Don’t Find Out About Until It’s Too Late
Summary: An estimated 68% of FERS personnel unknowingly leave over $120,000 on the table by relying on default L-Funds or failing to synchronize their agency match with retirement timing. Here is the verified executive breakdown before your next pay cycle.

Pay Special Attention to Mistake #5 (The TSP Spillover Trap)
Federal employees contributing to catch-up contributions after age 50 routinely trigger automatic match freezes without notification from payroll. Check the timeline below to protect your agency matching funds.
Free Public Educational Guide • No Login Required • Updated for Current Federal Pay Scale
FEDERAL RETIREMENT BENCHMARK
Standard TSP vs.
Optimized Planning
Leaving federal accounts on generic default settings often leads to hidden fee drag and missed compounding. Here is how standard management compares to a personalized blueprint.
CRITICAL RETIREMENT AUDIT FOR FEDERAL EMPLOYEES
7 Hidden Mistakes
To Avoid
If you are between ages 45 and 65, an unnoticed misallocation or timing miscalculation could silently reduce your lifetime annuity cashflow. Review these critical pitfalls before locking in your retirement packet.
Fleeing into the G-Fund Too Early Out of Panic
The false sense of security: When market turbulence strikes, thousands of federal employees panic-park 100% of their savings into the Government Securities Investment Fund. While the G-Fund guarantees no nominal balance loss, it exposes long-term retirees to ruthless purchasing power evaporation. If your portfolio fails to outpace cumulative healthcare and living inflation, your nest egg will deplete years sooner than expected.
CRITICAL REALITY CHECK: The 'Zero-Loss' Illusion
Over a 15-year retirement period, a portfolio held predominantly in the G-Fund during moderate 3.2% inflation forfeits an estimated 38% of real purchasing power. Safe preservation without targeted growth guarantees a silent annual downgrade in your standard of living.
Ignoring Life-Cycle Fund Glidepath Disconnects
The one-size-fits-all fallacy: L-Funds are pre-programmed algorithms designed for median civilian timelines, not the distinct realities of civil service pension earners. Because federal workers already possess a guaranteed lifetime FERS defined-benefit annuity, an L-Fund's automatic de-risking glidepath may lock your portfolio into an overly conservative formula long before your true distribution phase begins.
Borrowing via In-Service Loans During Peak Earning Years
The compounded opportunity drain: Taking residential or general-purpose loans against your balance removes critical capital during the compounding surge of your 50s. While you technically pay interest back to yourself, you lose compounding equity gains on the C and S funds. Worse, loan deductions often trigger reduced payroll matching contributions, leaving thousands in agency money on the table.
ADVISORY WARNING: The Double Taxation Mechanism
In-service loan repayments are executed using post-tax payroll dollars. When you eventually withdraw those same funds in retirement, they are taxed a second time as ordinary income. A $35,000 loan can carry a disguised tax friction far exceeding commercial bank rates.
Miscalculating the Special Retirement Supplement Gap
The sudden cashflow shock: Federal employees retiring under MRA+30 often rely heavily on the FERS Annuity Supplement to cover living costs until age 62. However, the supplement is subject to an earnings penalty if you accept post-retirement consulting or employment, and it abruptly ceases at 62. Without a pre-structured withdrawal bridge, you may be forced to liquidate equities during an ill-timed market dip.
Neglecting Systematic Portfolio Rebalancing
The unmonitored risk drift: During prolonged bull markets, equity holdings in the Common Stock (C) and Small Cap (S) funds swell disproportionately. A portfolio intended to maintain a 60/40 balance can unintentionally drift into an 85/15 posture. Failing to rebalance systematically leaves late-career personnel completely exposed to sudden market corrections directly before retirement.
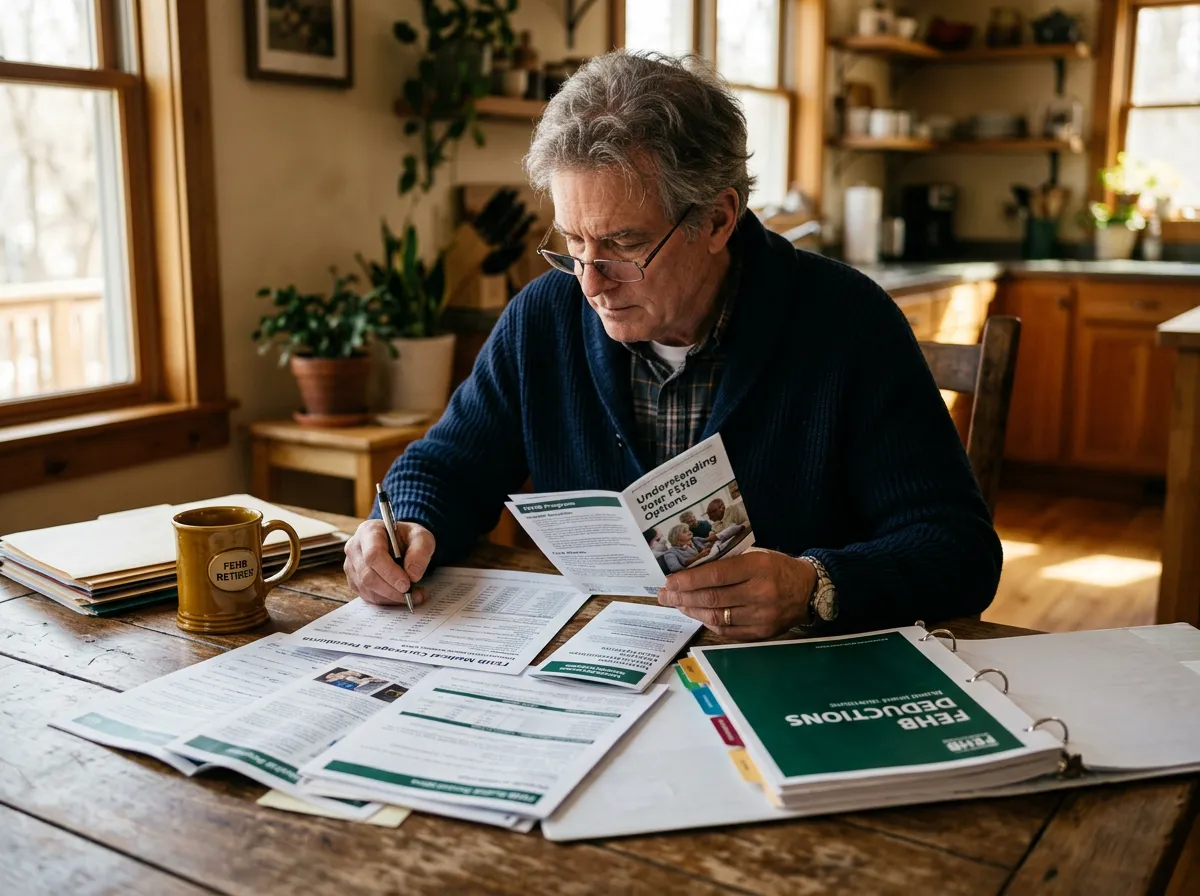
Overlooking FEHB Premium Deductions in Retirement
The post-tax healthcare deduction trap: While retaining Federal Employees Health Benefits into retirement is an exceptional privilege, premium payments shift from pre-tax payroll to post-tax annuity deductions. That subtle tax change, combined with rising medical inflation, consumes a significantly larger chunk of your net take-home pay than most calculators disclose.
Delaying Your Comprehensive Lifetime Income Audit
The costly cost of delay: Most civil servants wait until their final 90 days before submitting paperwork to stress-test their actual retirement cashflow. By then, correcting years of missed catch-up contributions, inefficient allocations, or suboptimal survivor benefit elections is impossible. Performing a personalized gap audit right now provides the runway necessary to maximize your benefits.
FAST-TRACK ASSESSMENT
Skip the Article &
Get Answers
If you already know your TSP allocation needs attention, don't wait until the end of the guide. Calculate your gap, compare your pension outlook, and discover your real retirement readiness in minutes.
No sensitive account numbers required • 100% complimentary for federal employees
BRIDGE THE GAP TO CONFIDENCE
Why Take The
TSP Check?
Stop guessing whether your current asset distribution aligns with upcoming federal deadlines. Get instant, objective insight before taking action.
RAPID DIAGNOSTIC
Completed in Under 120 Seconds
No account numbers, logins, or tedious documentation required. Six direct multiple-choice inputs deliver your tailored risk breakdown immediately.
PRECISION BENCHMARK
Calibrated to FERS & CSRS Rules
Built exclusively around federal retirement structures and specific Thrift Savings Plan fund dynamics, bypassing generalized commercial 401(k) models.
DIRECT IMPACT
Actionable Wealth Protection
Immediately discover if your nest egg is vulnerable to silent compound erosion, and isolate the exact positioning adjustments to safeguard your retirement.
Free assessment - 100% confidential - No government agency affiliation
🔒 PRIORITY 2026 TSP SCREENING
Priority 2026 Screening
Complete the confidential 60-second assessment below to analyze your current allocation risk, calculate retirement tier status, and generate your customized 2026 TSP strategy breakdown.
60-Second
Assessment
Zero Sales Calls
Guaranteed
2026 Updated
TSP Formulas
🛡️ Federal Employee Privacy Assurance: Your submissions are completely confidential, protected under strict 256-bit encryption protocols, and will never be shared with outside brokers or third-party marketers.
⚡ Limited Daily Allocations: Free priority analysis is restricted to 25 federal employee reviews per business day. There are currently only 4 slots remaining today.
VERIFIED SCREENING RESULTS
Trusted by Peers
Civil service professionals and military personnel who completed the self-screening review their key findings.
VERIFIED EMPLOYEE
★★★★★
"The screening flagged a major blindspot in my L-Fund allocation before my target MRA. Discovering my pension deficit calculation ahead of time saved my retirement horizon."
Marcus V.
VERIFIED EMPLOYEE
★★★★★
"I assumed my agency HR tracked every angle of my FERS annuity. The assessment spotted an uncredited military buyback window I would have forfeited forever."
Elena R.
VERIFIED EMPLOYEE
★★★★★
"Shockingly precise analysis. It proved how sequence-of-returns drawdown would hit my TSP during year one of retirement. Every civil servant needs to run this check."
David K.
OUR IRONCLAD COMMITMENT
100% Risk-Free
Assurance
Your complimentary TSP analysis is strictly informational, 100% free of charge, and carries zero obligation whatsoever. We operate as an independent retirement analysis organization and are completely non-affiliated with the federal government or the Thrift Savings Plan board. You maintain full ownership and control of your financial decisions at all times.
- Zero Fee Guarantee: The comprehensive assessment and report are 100% free.
- Strict Independence: Fully non-affiliated with the federal government or TSP board.
- No Obligation: You will never be pressured to purchase any financial product.
TRANSPARENCY & COMPLIANCE
Common Questions
Clear, direct facts regarding our independent status, privacy protocols, and analytical guidance for career federal personnel.
Is TSP Wealth Builder affiliated with or endorsed by the U.S. Federal Government?
No. TSP Wealth Builder is an independent educational publication and retirement strategy organization. We are not affiliated with, endorsed by, or operated by the Federal Retirement Thrift Investment Board (FRTIB), OPM, or any federal agency. All editorial materials, evaluation tools, and educational guides are provided strictly for independent informational planning.
How does this independent analysis differ from agency HR retirement briefings?
Agency HR specialists are administrators bound by strict statutory boundaries: they process paperwork and verify service calculations, but cannot legally provide personalized financial guidance or allocation advice. Our independent analysis evaluates the blind spots HR leaves untouched, helping you anticipate tax liabilities, distribution pitfalls, and timeline coordination.
Does reviewing my federal accounts require moving my money or transferring funds?
Never. Our assessment is 100% diagnostic and educational. You retain exclusive custody and management of all federal accounts at all times. The objective is simply to benchmark your allocation readiness, ensure you are not taking unintended volatility risk, and protect your hard-earned annuity.
How is my personal pension and service timeline information protected?
We enforce strict bank-grade 256-bit SSL encryption across all digital interfaces. We never sell, rent, or distribute your personal career milestone details to third-party telemarketers or external lead brokers. Your numbers remain confidential and are utilized solely to formulate your personalized readiness review.
HIGH-INTENT RETIREMENT ASSESSMENT
Skip the Article &
Get Answers
Don't spend 20 minutes reading when you can discover your exact federal pension forecast, hidden TSP gap, and penalty-free milestone in under 120 seconds.
256-Bit SSL Encrypted
Takes Under 2 Minutes
100% Confidential Data
© 2026 TSP Wealth Builder. All Rights Reserved. Dedicated to federal employee financial education.
Ready To Start?
Free 15-Minute Eligibility Review • 100% Confidential